Car insurance for delivery drivers is often different from a regular personal policy, and the gap can cost you a claim.
Below you will see what a personal policy usually excludes, what delivery platforms require, and how to close the gap.
Read to the end and you will know exactly what to ask your insurer before your next order.
Do you need special car insurance for delivery drivers
In most cases, yes. A standard personal auto policy typically excludes using your car to deliver goods for pay. Delivery drivers usually need an endorsement, a hybrid policy, or a commercial policy.
The Insurance Information Institute (III), an industry education organization, explains that personal auto policies are not designed, underwritten or priced for commercial use. It notes that they typically exclude “livery services”, which is the insurance term for carrying people or goods for a fee. Delivering groceries for an app falls on the business side of that line.
Here is how coverage usually splits across a delivery shift. Your own policy wording decides the details.
| Situation | What usually applies |
|---|---|
| App off, personal errand | Your personal auto policy |
| App on, waiting for an order | Gray zone; personal policy may exclude it |
| Shopping and driving to the customer | Business use; endorsement or commercial policy |
| Injury to you while working | Health insurance or platform accident coverage, if offered |
The III describes the same problem for rideshare drivers in three periods: app on but no match, match accepted, and passenger in the car. For delivery, replace the passenger with an order. Coverage can differ in each period, and the personal policy is the one most likely to say no.
That is the rule on paper. The next section shows what it means on the day you actually need to file a claim.
What changes the day something goes wrong on a delivery
Without the right coverage, a delivery accident can turn into a denied claim, a canceled policy, and repair bills paid out of your own pocket.
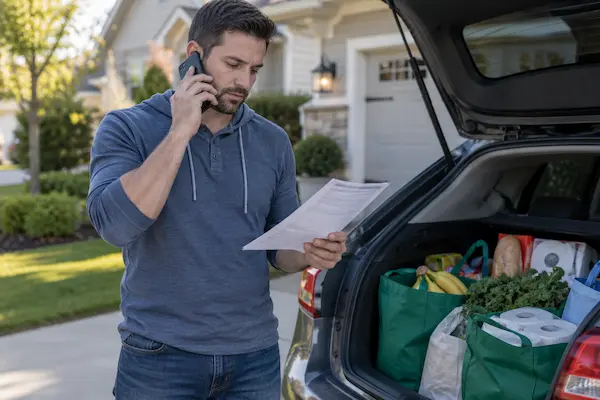
Think about a normal week. You shop an order, load the bags, and drive across town. A driver runs a light and hits your rear door. You call your insurer, and the first question is what you were doing at the time. If the answer is “delivering an order” and your policy excludes business use, the claim may be refused.
Illustrative example: a driver with a personal-only policy is rear-ended while carrying groceries. The other driver is at fault, so their insurer pays for the car. But the delivery driver’s own insurer learns about the app work and does not renew the policy. Finding new coverage after a non-renewal costs more.
Now the same accident with a delivery endorsement on the policy. The insurer already knows about the app work. The claim is handled like any other, and the renewal arrives as usual. The monthly cost of the endorsement was small next to that outcome.
⚠️ Attention: hiding delivery work from your insurer is not a shortcut. If it comes out during a claim, the insurer may deny the claim and cancel the policy. That history follows you to the next quote.
What the platforms themselves require is the next piece, because it is less than most drivers assume.
What delivery platforms require and what they cover
Delivery platforms generally require you to carry your own auto insurance as a condition of signing up. Most do not insure your car for you.
Shipt’s help center is a clear example. Its list of requirements includes being at least 18 years old, a valid U.S. driver’s license, a Social Security number, auto insurance, a reliable and operable vehicle, a smartphone, and the ability to lift 50 pounds. Insurance is listed as something you bring, not something the platform provides.
The same help center has a page for shoppers who have a car accident on the way to shop or deliver. It says to contact the authorities first, document what happened, and then reach Shipt support. It does not promise to cover the vehicle. Other grocery and food platforms publish similar requirements in their sign-up pages, and some offer limited coverage only while an order is active. Read the exact terms of any platform you drive for.
Before you accept the first order, get answers to these questions from your own insurer.
The III notes that a handful of insurers in some states now sell policies that cover a car used both privately and for app work. It also says drivers can add a rider or endorsement to a personal policy for periodic app use. Its advice is to contact your own insurer to address any gaps. With those answers in hand, the fix is a short process.
How to get the right delivery driver insurance step by step
Have your current policy declarations page, your driver’s license, and the names of the apps you use ready, because every insurer will ask for them.
- 1Read your policy’s exclusions and find the wording on business use, livery, or delivery. That paragraph is your starting point.
- 2Check the platform’s terms for any coverage it provides while an order is active, and note where it starts and stops.
- 3Call your insurer and ask the five questions above. Ask for the answer in writing, by email or in the policy documents.
- 4Compare two or three quotes for a delivery endorsement or a hybrid policy, using the same coverage limits so the prices mean something.
- 5Add the endorsement or switch policies before your next shift, and keep the proof of insurance in the car and in the app.
- 6Review once a year or whenever you add a new app, since heavier use can push you from an endorsement into commercial territory.
Three mistakes are common. Drivers assume the platform’s coverage protects their own car. They buy an endorsement for one app and drive for three. And they drop collision to save money right before a busy season. If your insurer does not offer an endorsement, ask an independent agent which carriers in your state do. This is general information; a licensed agent or your state insurance department can confirm what applies to you.
Frequently asked questions about gig driver insurance
These are the questions delivery drivers ask most before they sign up.
Do I need delivery insurance if I only drive a few hours a week?
Hours do not change the exclusion. The III explains that personal policies typically exclude livery, whether you deliver once or daily. The difference is the fix: light use often fits an endorsement, while full-time delivery may require a commercial policy. Ask your insurer where the line is.
Is rideshare insurance for delivery the same thing?
Not always. Some rideshare endorsements cover only carrying passengers, while others include delivering goods. Read whether the endorsement names “delivery” or “transportation of goods”. If it only mentions passengers, it may not respond to a grocery run.
Does the delivery company’s insurance cover my car?
Usually not. Platforms like Shipt list your own auto insurance as a sign-up requirement. Where a platform offers coverage, it is often limited to liability while an order is active, and it may not pay to repair your vehicle. Check the platform’s terms and confirm with your insurer.
How much does gig driver insurance cost?
Prices vary by state, insurer, driving record and vehicle, so there is no single number. Endorsements are usually a monthly add-on to an existing policy; commercial policies cost more. Get quotes with identical limits from at least two insurers and compare the yearly total.
What should I do right after an accident on a delivery?
Follow the order Shipt gives its shoppers: contact the authorities, document the scene with photos and the other driver’s details, then report to the platform. Report to your own insurer as well, and be accurate about the fact that you were on a delivery.
How this site helps you earn safely with delivery work
The Productivity section of en.amucc.com.br covers the practical side of gig work, from signing up for delivery apps to keeping the income after expenses.
Insurance is the topic drivers skip most often, so this guide exists to make the questions simple. The same section explains how grocery and food delivery platforms pay and what a driver can deduct. It also shows how to plan a week of shifts around the hours that earn most.
✅ How we checked this information: the policy exclusion and coverage-period facts come from the Insurance Information Institute’s guidance on ride-sharing and insurance. Platform requirements come from Shipt’s shopper help center. Rules and offerings vary by state and insurer; confirm with a licensed agent.
Nothing here is legal or insurance advice. It is the list of questions a careful friend would tell you to ask before you take the first order.
Make the call before your next order
You asked whether you need special car insurance for delivery drivers. The honest answer is that your personal policy probably excludes it, and the fix is one phone call.
Do it today. Pull up your policy, find the business-use exclusion, and call your insurer with the five questions from this page. Ask for a delivery endorsement or a hybrid policy quote, and get the answer in writing. The next order you accept will be one you are actually covered for.
Keep reading the Productivity section for guides on delivery app pay, expenses and scheduling.
ℹ️ Important: en.amucc.com.br is an independent site, not affiliated with any government agency or company mentioned, including Shipt and the Insurance Information Institute. This content is informational only and is not insurance, legal or financial advice. Policy terms vary by state and insurer; confirm with a licensed professional.