A gig worker taxes set aside routine means moving a fixed slice of every payout into a separate account each week.
Most gig drivers who get a surprise tax bill made one mistake: they treated the app payout as take-home pay.
Read to the end and you will have a weekly percentage, a place to park it, and the IRS dates to pay it out.
How much should gig workers set aside for taxes each week
A common working rule is to set aside 25% to 30% of your net gig earnings (what is left after mileage and other business expenses) every week, then adjust after your first quarterly payment. The exact number depends on your income, your state, and whether you also have a W-2 job with withholding.
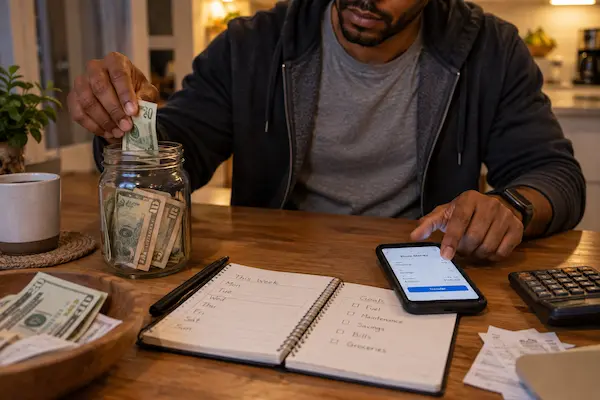
The reason the slice is that large: gig income carries two federal taxes at once. The Internal Revenue Service (IRS) states that the self-employment tax rate is 15.3%, made up of 12.4% for Social Security and 2.9% for Medicare. On top of that comes regular federal income tax at your bracket, and in many states, state income tax too.
The IRS also makes clear that you must report income earned from the gig economy on a tax return even if it is part-time, side work, paid in cash, or not reported on a Form 1099-K, 1099-NEC, or any other statement. The app not sending a form does not mean the IRS does not expect the tax.
Here is a starting-point table. It is a planning guide, not tax advice; a tax professional or the IRS worksheets in Form 1040-ES give you your real number.
| Your situation | Weekly set-aside (of net gig profit) |
|---|---|
| Gig is your only income | About 25% to 30% |
| Gig plus a W-2 job | About 20% to 30%, or raise W-4 withholding |
| State with no income tax | Toward the low end of the range |
| High-tax state or high earnings | Toward the high end, or above |
Those percentages apply to profit, not to gross payouts. Tracking mileage and expenses lowers the profit the tax is calculated on, which is why the weekly routine starts with a log. First, look at what it changes.
What changes when your gig worker tax savings run on autopilot
With a weekly set-aside, tax season becomes a transfer from an account that already holds the money, instead of a scramble for cash you spent months ago.
Illustrative example: a delivery driver spends every payout on rent, gas, and groceries. In April, a tax preparer explains that self-employment tax plus income tax adds up to a bill the driver cannot cover. The driver spends the next year paying last year’s taxes while this year’s keep piling up.
Now the same driver moves a fixed percentage of each week’s net profit into a separate savings account the morning the payout lands. Four times a year, the driver sends an estimated payment from that account. In April, the return shows a small balance or a small refund. The bridge between the two years is a rule the driver set once and a transfer that takes 30 seconds.
The IRS is explicit that estimated tax is how self-employed people pay as they go. Individuals generally have to make estimated tax payments if they expect to owe $1,000 or more when they file. Missing those payments can mean a penalty on top of the tax, which is the part that makes an ignored tax bill grow.
⚠️ Attention: keep the tax account separate from your spending account and from your emergency fund. Money that is visible in the same balance gets spent. A plain savings account at your bank with no card attached works well.
To size the slice correctly, you need to know what the tax bill is made of. That is the next section.
What gig income taxes actually include
Your gig tax bill has three layers: self-employment tax, federal income tax, and, in most states, state income tax. Each is calculated on your net profit after business expenses.
Self-employment tax. The IRS states that you must pay self-employment tax and file Schedule SE if your net earnings from self-employment were $400 or more. The rate is 15.3% in total. You can deduct the employer-equivalent portion of that tax when figuring your adjusted gross income, which slightly lowers your income tax, though not the self-employment tax itself.
Federal income tax. This is the same bracket-based tax everyone pays. Gig profit gets added to any other income, such as W-2 wages, so your rate depends on the whole picture.
State and local tax. Rules vary widely. Some states have no income tax; others tax self-employment profit like any other income, and a few cities add their own. Check your state’s revenue department site.
What lowers all three: expenses. The IRS gig economy guidance tells workers to keep records and identify deductible business expenses. For drivers, mileage is usually the biggest one. The IRS publishes a standard mileage rate per business mile that changes over time; look up the current rate on IRS.gov and log every business mile from the day you start. Phone costs used for work, hot bags, and app fees are other common deductions.
The IRS says you generally avoid an underpayment penalty if you owe less than $1,000 after withholding and credits, or if you paid at least 90% of the current year’s tax or 100% of the prior year’s tax, whichever is smaller. That “prior year” option is useful: if you paid the same total as last year through estimates, you are usually protected even if you earn more this year. Now, the weekly routine.
How to set money aside for gig taxes each week step by step
You need a separate savings account, a mileage log (app or notebook), and your payout schedule. Set up the account before your next payout so the first transfer happens on time.
- 1Open a separate savings account named “Taxes” with no debit card, at your current bank or an online bank.
- 2Log every business mile and expense the same day, so your weekly profit number is real and not a guess.
- 3Calculate the week’s net profit on payout day: total payouts and tips minus mileage (miles times the current IRS rate) and other expenses.
- 4Transfer your percentage (start at 25% to 30% of net profit) to the Taxes account before you spend anything else.
- 5Pay estimated tax each quarter from that account using Form 1040-ES, IRS Direct Pay, or your IRS online account, on the four IRS due dates.
- 6Adjust the percentage after the first quarter: if the account holds far more than you paid, lower it a little; if it fell short, raise it.
Common mistakes: applying the percentage to gross payouts and starving your budget, skipping the mileage log and overpaying, and forgetting that the IRS lets you change estimated payments each quarter if your income changes. If you also have a W-2 job, another route is to increase withholding on your W-4 so your paycheck covers the gig tax; the IRS Tax Withholding Estimator accepts self-employment income in its calculation.
Frequently asked questions about how much to save for taxes on gig work
How much should I save for taxes on gig work if I made very little?
The IRS says self-employment tax applies once net earnings reach $400 or more, and income must be reported regardless of amount. For small side income, setting aside about 20% still protects you, and you will get the excess back at filing.
Do I have to pay quarterly, or can I pay it all in April?
The IRS generally requires estimated payments if you expect to owe $1,000 or more, and paying only in April can trigger an underpayment penalty for the earlier quarters. Weekly set-asides plus four quarterly payments avoid that.
Does the app take taxes out of my gig payouts?
Usually no. Most gig platforms treat you as an independent contractor and do not withhold federal tax. Whatever lands in your account is pre-tax, which is exactly why the weekly set-aside exists.
Where should I keep my gig worker tax savings?
In a separate savings account with no card, ideally one that earns some interest. Keep it apart from your emergency fund so a car repair never eats the money you owe the IRS.
What if I did not get a 1099 from the platform?
You still owe tax on the income. The IRS states that gig income must be reported even when it is not shown on a Form 1099-K, 1099-NEC, or other statement. Use your own payout records from the app.
How this site helps gig workers stay organized
Our Productivity section is built for people whose income arrives in daily or weekly chunks: delivery drivers, rideshare drivers, shoppers, and freelancers. Taxes are the part of gig work nobody explains at signup, so we break the rules into weekly habits you can keep on a phone.
Alongside this guide you will find pieces on mileage tracking, separating business and personal money, and planning around slow weeks.
✅ How we checked this information: the reporting rule for gig income comes from the IRS Gig Economy Tax Center; the 15.3% rate, the $400 threshold, and the employer-equivalent deduction come from the IRS self-employment tax page; the $1,000 estimated tax rule, Form 1040-ES, payment methods, and the 90%/100% penalty safe harbor come from the IRS estimated taxes page. The set-aside percentages are a planning range, not an IRS figure.
For your actual numbers, use the IRS worksheets or consult a tax professional.
Start your weekly tax set-aside this week
You came here to build a gig worker taxes set aside habit, and you now have it: log miles daily, calculate net profit on payout day, move 25% to 30% into a separate account, pay the IRS quarterly, and adjust after the first quarter. The bill in April stops being a surprise.
Open the savings account today, before your next payout. Then look up the current IRS mileage rate and the four estimated tax due dates on IRS.gov and put them in your calendar. When that is done, browse our other Productivity guides to make the rest of your gig income just as predictable.
ℹ️ Important: en.amucc.com.br is an independent informational site, not affiliated with any government agency or company mentioned, including the IRS or any gig platform. This article is general information, not tax advice. Rates, thresholds, and due dates can change; confirm current figures on IRS.gov or with a tax professional.